A developer works alongside holographic AI assistants in a busy modern office.
Model selection is a key part of AI cost management and overall governance. Each AI variant has multiple models – for example Claude has Fable, Opus, Sonnet, and Haiku – and each is the better option for different tasks and outcomes. This is a balance of capabilities, speed, accuracy, and price and will vary across different requirements and different times.
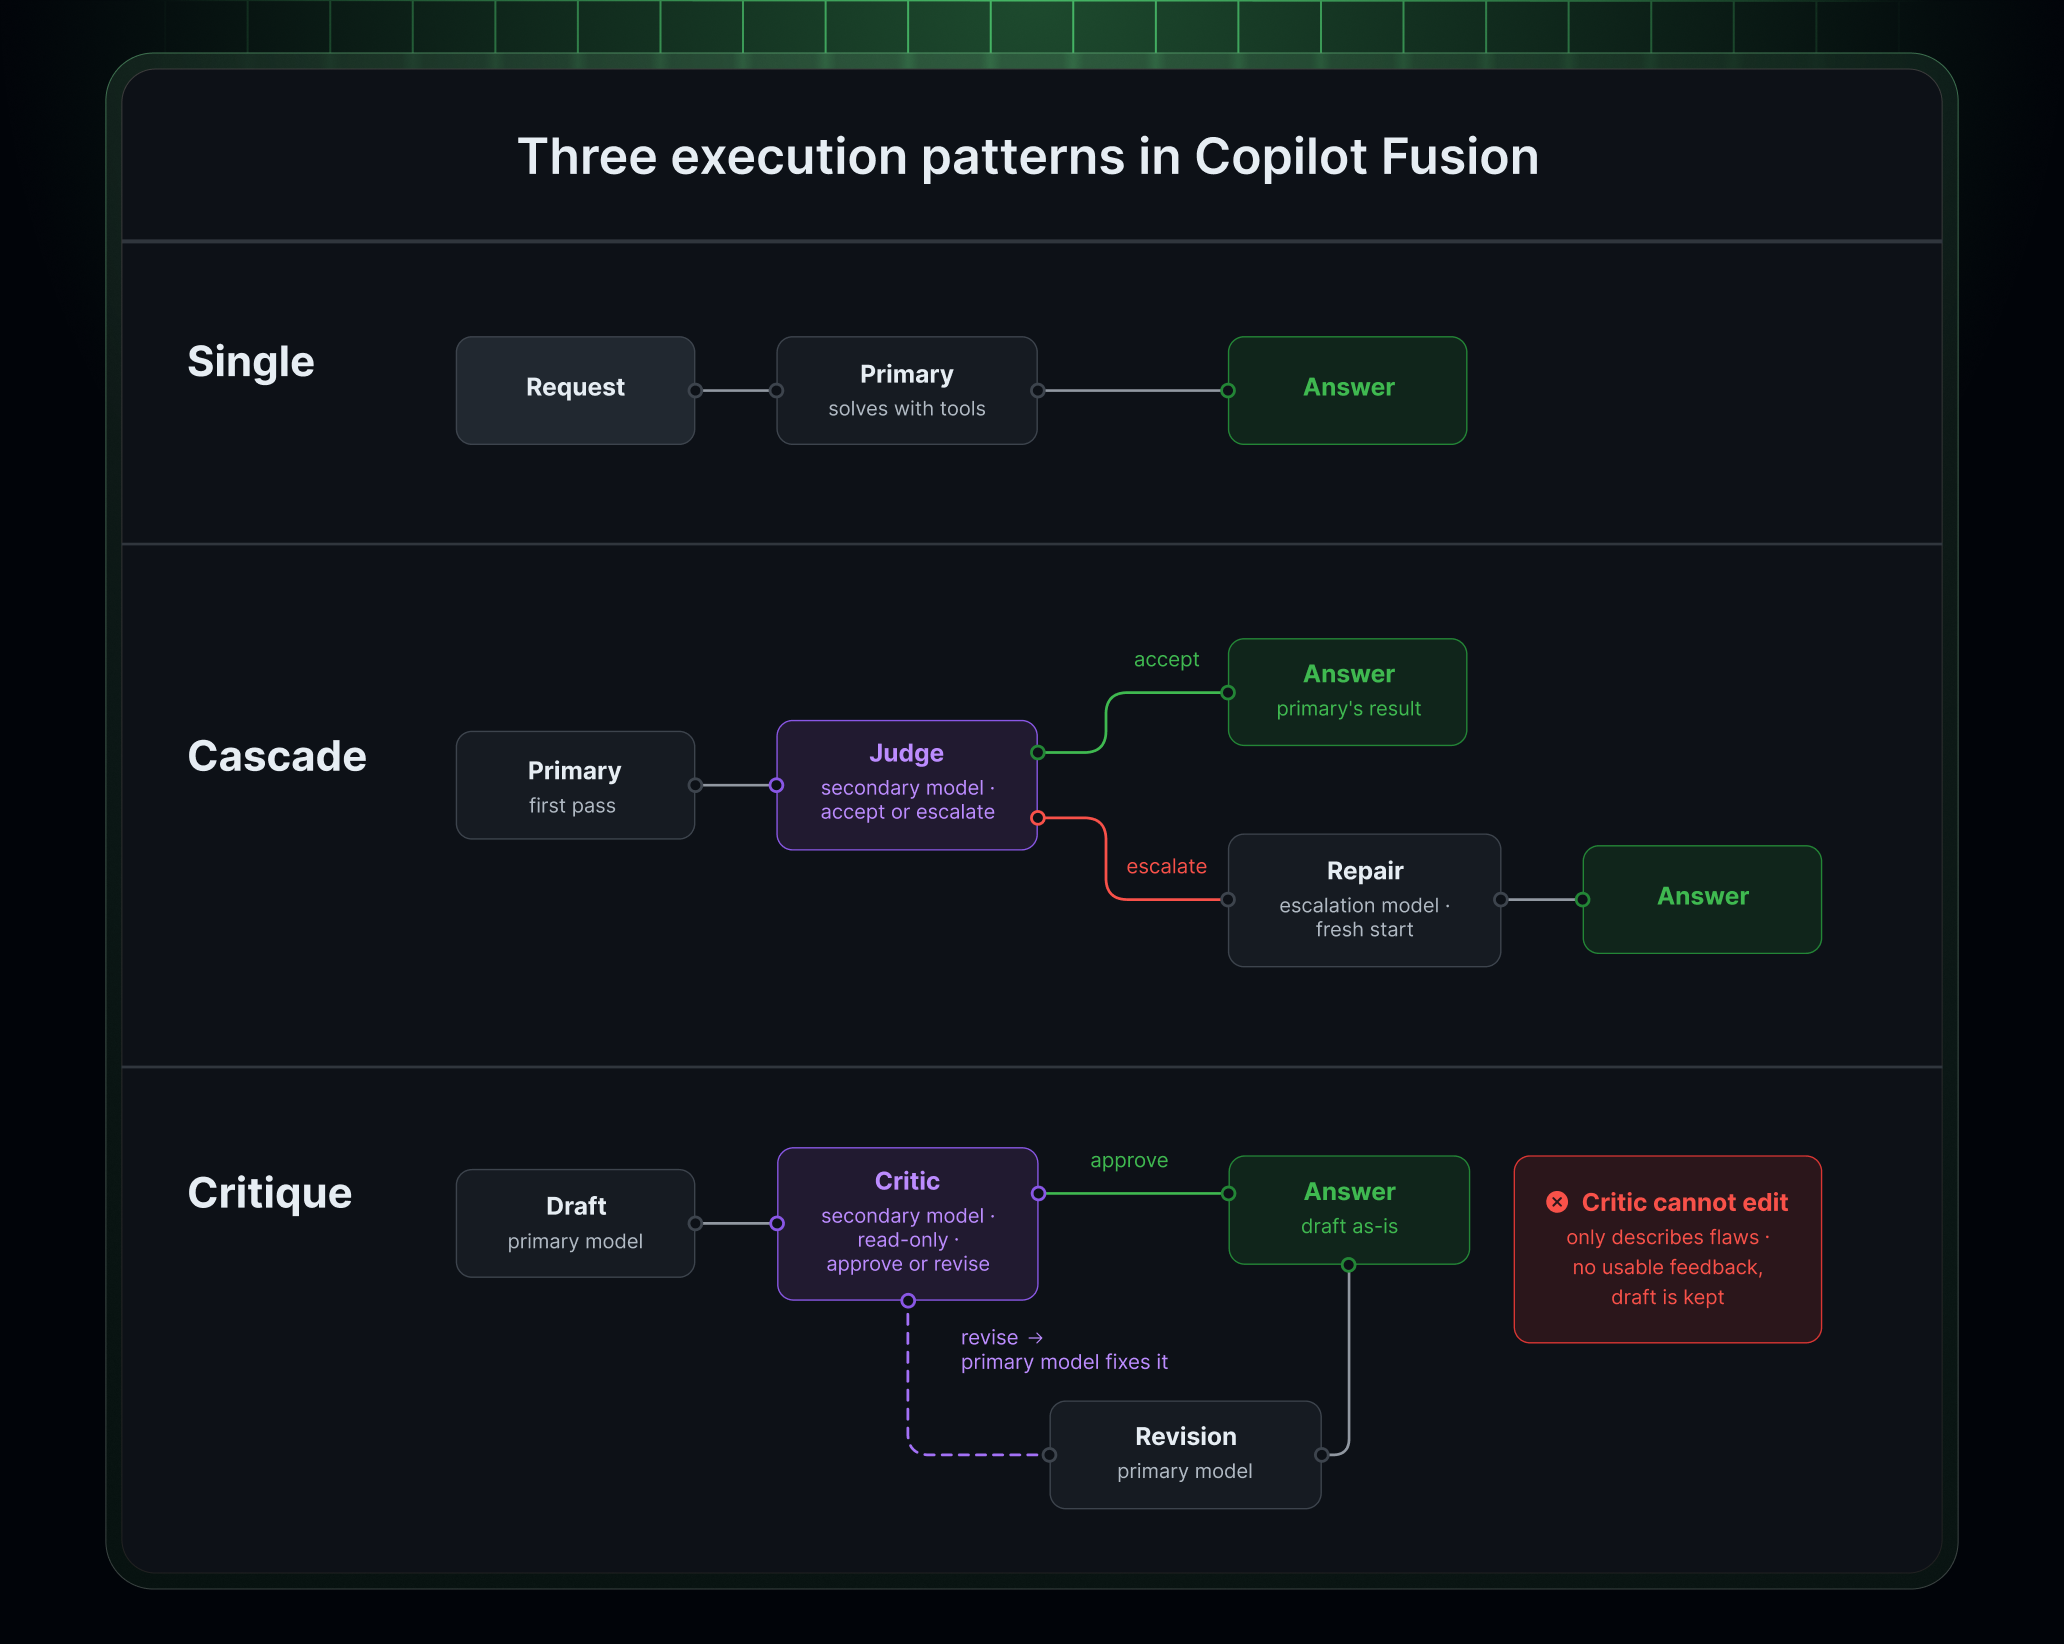
Even when organisations & users are aware of model selection as a consideration, choosing which model to use and when can be difficult. Microsoft have introduced their answer to this with GitHub Copilot Fusion, where rather than the developer picking the best model to use – Copilot does. They say:
“When you select Copilot Fusion in the model picker, you aren’t selecting a specific model. You’re choosing a system that routes and orchestrates models for each task. There’s no need to switch models during a task or decide which model suits each step. For each prompt, Copilot Fusion determines which models to use and how they work together, while you choose the right level of effort.
disable models for Copilot Fusion without disabling the model for everyone
How is GitHub Copilot Fusion billed?
There is no additional charge for Fusion. The main thing to be aware of is that, if it chooses to use multiple models, you will be billed for multiple models.
Through the month of November 2026, for users with a paid GitHub Copilot plan – there is a 30% discount on model costs when using Fusion.
I am interested to see if Fusion brings about a significant reduction in cost/improvement in performance for many organisations.
Pip: Welcome to Cloudy with a Chance of Licensing — where the forecast is partly cloudy with a strong chance of your Azure bill going up.
Mara: rich_gibbons has been tracking some significant changes across Azure pricing, reservation policy, and Copilot Studio this episode, alongside Microsoft's latest financial results. There's a lot that touches FinOps and ITAM teams directly.
Pip: Let's start with what February 2027 is quietly turning into: a deadline with teeth.
Azure Prices and Reservation Policy: February 2027
Mara: Two separate but converging changes land on the same date — February 1st, 2027 — and together they reshape how organizations should be thinking about their Azure commitments right now.
Pip: The price increases hit seven regions, and the spread is meaningful. Dublin leads at 17%, Singapore sits at the low end with 8%, and France, Amsterdam, and Norway fall in between.
Mara: The post is direct about the action item: "If you're heavily in these datacentres, particularly Dublin, modelling your bills next year — and potential mitigations — should be on the list for FinOps and ITAM teams."
Pip: Seventeen percent is not a rounding error. That's a real budget conversation waiting to happen, and the exclusion lists don't make it simpler — there are long lists of VM series and storage services carved out, so teams need to check their specific footprint carefully.
Mara: And the reservation exchange policy post explains exactly why that footprint review matters even more now. From February 1st, 2027, Azure Reservations for Virtual Machines, App Service, SQL Database, and similar services will no longer be exchangeable if a Savings Plan exists for that service.
Pip: This change has been announced, postponed, and re-announced since October 2022 — it's had more false starts than a budget approval cycle.
Mara: That history is worth noting. It was pushed from January 2024 to July 2024, then deferred indefinitely, with Microsoft promising six months' notice before re-implementing. That notice has now been given, and the post suggests another postponement seems unlikely.
Pip: So the flexibility organizations relied on — swapping reservations when workloads shifted — is going away for most compute services.
Mara: The post frames the strategic choice clearly: Savings Plans offer lower maximum discounts but much less administrative overhead and no need to manage exchanges. Reserved Instances still deliver higher discounts for stable, predictable workloads, but the safety valve of exchangeability is closing. Strategies need to be reviewed before that door shuts.
Pip: Two changes, one date — the financial modeling homework is overdue.
Microsoft's Q1 FY27 Numbers
Mara: Microsoft's first quarter FY27 results are out, and the headline figures are substantial — revenue of $92.3 billion, up 19%, with net income up 32% and Microsoft Cloud revenue reaching $63.9 billion.
Pip: Azure grew 48% year over year, which does make the price increases feel a little less like necessity and a little more like confidence.
Mara: Satya Nadella described Copilot's direction plainly: "We think of Copilot as the new OS for work." The results show consumption billing — particularly through GitHub Copilot and M365 Copilot — as a primary growth driver, with usage-based billing customers up over 75% in the quarter.
Pip: Speaking of usage-based billing — that's exactly where the next story lives.
Copilot Studio's New Harness and Its Billing Catch
Mara: Copilot Studio now has a third option for building agents — the GitHub Copilot harness — which brings the same coding and reasoning capabilities as GitHub Copilot and Copilot Cowork to your in-house agents.
Pip: The capability sounds useful. The billing model is the part that deserves a careful read before anyone starts building.
Mara: The post quotes Microsoft directly: "Agents running on the GitHub Copilot harness use usage-based billing for all work, regardless of Microsoft 365 Copilot licensing." Unlike the existing harnesses, where Copilot Credits are covered by an M365 Copilot license, this one draws on pre-purchased credits or incurs pay-as-you-go costs.
Pip: No one is being forced onto this model — it's an optional, additional capability. But "optional" and "inadvertent spend" have a way of meeting each other quietly.
Mara: The Copilot Studio Licensing Guide for August 2026 is worth reviewing alongside this, and the post is clear that strong internal governance and awareness programs are the practical response here.
Mara: February 2027 keeps appearing as the date when several assumptions about Azure cost management stop holding — pricing, reservations, and consumption billing are all moving at once.
Pip: Next time, hopefully the forecast includes at least one change that makes the bill smaller. We'll be watching.
Microsoft’s results for FY27 Q1 are out and, once again, the numbers are bigger than last time. It’s always difficult to reconcile such huge results with layoff announcements and that has happened again with news that Microsoft have made a voluntary exit offer to approx. 60,000 staff – almost a quarter of the workforce.
Talking about the recent Copilot “super app” that combines Chat, Cowork, Autopilot, and Code, Satya Nadella said “We think of Copilot as the new OS for work” – make of that what you will!
It’s clear that AI, Copilot, and consumption billing are the big drivers of Microsoft’s revenue and future direction.
Revenue = $92.3 billion, up 19%
Net Income = $36.6 billion, up 32%
Microsoft Cloud revenue = $63.9 billion, up 30%
For several years, revenue has been split into different categories:
Productivity and Business Processes
Intelligent Cloud
More Personal Computing
but it now seems to be:
Agents and Infra
Devices and Consumer
so the Agents & Infra segment includes Azure and M365. I assume it will include Dynamics 365 too but, for the first time in a long time, that isn’t mentioned specifically…does that mean D365 hasn’t grown in Q1 FY27?
Nadella did say that they’re “bringing the business logic and capabilities of Dynamics 365 directly into Copilot and helping every organization stand up their own infinite SaaS Factory” – perhaps there’s a shift in focus happening?
Amy Hood, CFO, stated that:
“Capital expenditures were $45.2 billion,. Roughly three quarters of…capex was for short-lived assets, primarily CPUs and GPUs, including higher memory and storage costs.”
That’s over $33 billion on CPUs and GPUs in a single quarter!
Agents & Infra numbers
Revenue increased 25% to $76.8 billion
Azure revenue grew 48%
M365 Commercial increased 17%
M365 Copilot, E5, and E7 helped drive higher average revenue per user as well as more consumption billing, particularly of GitHub Copilot.
Earnings Call highlights
The number of Copilot customers actively consuming credits through usage-based billing grew over 75 percent over the quarter.
Credit consumption from agentic features on GitHub has more than doubled since usage-based billing went into effect.
Over 44,000 paid Fabric customers, up more than 50 percent year over year.
Microsoft added 24 new data centers across five continents this quarter.
From 1 February 2027, Microsoft will raise prices for specific Azure Virtual Machine series and Azure Storage services in seven regions, by between 8% and 17%.
Regions and increases
Dublin takes the largest rise at 17%, and Singapore the smallest at 8%:
EU North (Dublin)
17%
France Central
11%
France South
11%
EU West (Amsterdam)
9%
Norway East
9%
Norway West
9%
Southeast Asia (Singapore)
8%
Microsoft has published an exclusion list as follows:
Excluded Virtual Machine series:
v1: Bv1, D, Ds, F, Fs, G, Gs, L, NP, HCS
v2: Av2, Amv2, Dv2, Dsv2, Fsv2, Lsv2
v7: Dsv7, Ddsv7, Dlsv7, Dldsv7, Esv7, Edsv7
Excluded Azure Storage services: Container Storage, Managed Lustre, NetApp Files Cross Region Replication SKU, Blob Features, Change Feed, General Block Blob, Import/Export, Queues, Queues v2, Standard Page Blob, Storage Actions, Storage Bandwidth, Storage Discovery, Tables and the Transaction Optimized SKU.
If you’re heavily in these datacentres, particularly Dublin, modelling your bills next year – and potential mitigations – should be on the list for FinOps and ITAM teams.
Remember, this is the same date (Feb 1, 2027) that the reservation changes kick in too.
Private GA of Azure Future Capacity Reservations added…”Azure Future Capacity Reservations allow Customers to request capacity for specified Microsoft Azure resources in a specified region, with a scheduled start date and reservation term”
A robed traveler confronts a luminous cloud gateway surrounded by digital data streams and futuristic servers.
Azure Future Capacity Reservations have been added to the Product Terms – these “allow Customers to request capacity for specified Microsoft Azure resources in a specified region, with a scheduled start date and reservation term“.
This seems a way of alleviating concerns over lack of capacity in certain regions and giving Microsoft more information with which to make resource and capacity increase decisions.
How do they work?
You request: A specific amount of Azure capacity, in a region, starting on a future date, for a set term.
Microsoft decides: They can accept, reject, or modify the request, normally within 7 days.
Availability: Microsoft tries to provide the capacity on the agreed start date. If they can’t provide all of it, they have 30 days to fulfil the remainder.
You can’t change it: Once accepted, you can’t modify it during the 12 weeks before the start date or the 30-day fulfilment period.
You pay for what they provide: Whether you actually use the capacity or not. Equally – you don’t pay for what they don’t provide.
If Microsoft can’t provide it: You can cancel the unfulfilled portion after the 30-day fulfilment period.
No compensation: Generally, Microsoft doesn’t owe you service credits for failing to provide the capacity.
No discount: This is capacity assurance, not a price discount, and doesn’t give you dedicated hardware.
You still have to do the admin: Subscription, quota, deployment and configuration requirements remain your responsibility.
End of term: The reservation expires and subsequent usage is charged at the then-current consumption rates.
Microsoft’s financial year ended on June 30, 2026 and, as usual, there aren’t many surprises. Microsoft continues to make an enormous amount of money, Azure continues to grow at a strong rate, and AI is still absolutely everywhere.
But there are a few things in these results that are particularly interesting from a licensing and FinOps perspective.
So, let’s dive in.
The headline numbers
For the full financial year:
Revenue = $331.8 billion, an increase of 16%
Net Income = $133.7 billion, an increase of 31%
Azure revenue surpassed $100 billion
Microsoft 365 Copilot has more than 30 million paid seats
So, yes, Microsoft is still generating an insane amount of money and the Q4 numbers were also pretty impressive:
Revenue = $90 billion, up 18%
Net Income = $35.8 billion, up 31%
Microsoft Cloud revenue = $59.3 billion, up 27%
Alongside this, Microsoft’s investment in AI infrastructure continues at quite a pace:
Capital expenditure increased by 70% to $41 billion in Q4, with Microsoft saying this was to support demand for cloud and AI offerings. Around two-thirds of that spending- almost $27 billion – was on CPUs and GPUs.
That level of spending contributed to a 23% decrease in free cash flow for the quarter, although Microsoft still generated $19.6 billion. When software vendors need money, they look to their customers so this big CAPEX outlay is likely to have an impact on pricing and discounts.
AI is still the focus
Satya Nadella’s opening comments were very much in line with what we’ve been hearing from Microsoft for the last couple of years.
He said:
“We are advancing the frontier on the cost-to-outcome curve, ensuring every customer can turn tokens into business results”
I think that wording is interesting.
There is obviously still an enormous focus on AI consumption, but Microsoft (and everyone else involved with AI) increasingly needs to talk about the value customers are getting from that consumption.
It’s one thing to tell organisations that they can use millions of tokens. It’s another thing to explain what those tokens actually achieved.
Satya also talked about two goals for Microsoft:
Making sure AI empowers people and increases their ability to achieve what they want to achieve.
Helping organisations build their own continuous learning loops without outsourcing their core intellectual property.
To support this, Microsoft has added 31 new datacentres across five continents, bringing the total to 88.
So the investment in infrastructure isn’t slowing down. Where is the money coming from?
Microsoft 365 and Copilot
Microsoft says that hundreds of enterprise customers have already purchased millions of Microsoft 365 E7 seats.
Alongside E5 and Copilot, this is helping drive ARPU — Average Revenue Per User growth.
And that is an important metric for Microsoft. As I’ve mentioned in previous posts, Microsoft doesn’t just want more customers. It wants to make more money from each customer and E5, Copilot, and now E7 are all part of that strategy.
Microsoft 365 Commercial revenue increased by 14% for the full year, while seats increased by 6%, driven by SMB and F-SKUs.
M365 Copilot has now passed 30 million paid seats. Of course, it’s still only a proportion of the overall Microsoft 365 user base, so there is potentially a lot more growth available if Microsoft can convince customers to roll Copilot out more widely.
Consumption is becoming increasingly important
This is probably the bit of the results that we all need to pay the most attention to.
Microsoft is continuing to move away from a world where software is simply purchased as a fixed number of licences. Consumption is becoming a much bigger part of the Microsoft business.
For example, Microsoft says that usage-based credit consumption for Dynamics 365 Customer Service increased fourfold quarter over quarter.
And GitHub Copilot switched to a consumption model on June 1 where Microsoft says it has already seen “significant consumption revenue” since the new model came into effect.
This is something I’ve been banging on about for a while now.
The traditional software licensing model was relatively easy to understand:
How many users do you have? Multiply that by the price per user.
Consumption changes that.
Now you need to understand what people are doing with the software, how much they are using it and what that usage is costing. AI is accelerating this shift dramatically.
Microsoft clearly believes this is working — and I expect we’ll see much more of it.
Productivity & Business Processes
The Productivity & Business Processes segment generated $37.8 billion, up 14%.
Within that:
Microsoft 365 Commercial revenue increased 14%
Microsoft 365 Commercial seats increased 6%
Dynamics 365 revenue increased 13%
Again, the important thing here is that Microsoft is getting growth from both more users and increased revenue from those users.
The move towards E5, E7 and Copilot gives Microsoft plenty of opportunities to increase ARPU without necessarily needing a corresponding increase in seat numbers.
Intelligent Cloud
Intelligent Cloud revenue was $39.3 billion, an increase of 32%.
Azure revenue increased by 43%.
And for the full financial year, Azure passed the rather significant milestone of $100 billion in annual revenue.
Databases are growing
Microsoft says cloud databases are surging, driven by AI systems’ need for access to data.
PostgreSQL revenue increased by 55%.
Microsoft is also launching Horizon DB, a new fully managed PostgreSQL service in Azure.
This makes sense. AI might be the headline story, but AI needs data. Lots of it. That means databases, storage and all of the other services supporting AI workloads stand to benefit from the growth in AI consumption.
Microsoft Fabric
Microsoft Fabric now has more than 40,000 paid customers.
That’s up from 35,000 just a few months ago. Fabric is another good example of Microsoft’s broader strategy: bring multiple capabilities together, make them easier to consume and then monetise the consumption.
Agent 365
There are now almost 40 million agents registered in Agent 365.
We’ve gone from talking about individual users having Copilots to organisations having thousands of software agents doing work on their behalf.
And that creates a whole new set of questions.
Who owns the agent?
How do you control what it can access?
How do you measure what it is doing?
And, perhaps most importantly, how much is it costing?
If software moves from being something a person uses to something that can operate autonomously, the traditional per-user licensing model becomes increasingly difficult to apply.
So what does this mean for customers?
There are three things that stand out to me from these results.
1. AI isn’t slowing down
Microsoft is spending enormous amounts of money building the infrastructure required to support AI.
The $41 billion quarterly capital expenditure figure tells you that.
Microsoft clearly believes the demand is there. We’ll find out if they’re right in a couple of years.
2. Consumption billing is coming for more of your Microsoft estate
If you’re still thinking about Microsoft licensing purely in terms of users × licences × price, you’re going to increasingly find that model doesn’t describe what you’re actually buying.
Now we’re seeing the same approach spread into Dynamics, GitHub Copilot, Microsoft 365 and AI services.
That means FinOps and ITAM are going to have to work increasingly closely together.
3. The value question is becoming more important
Microsoft isn’t just talking about AI adoption anymore.
They’re talking about the cost-to-outcome curve. Customers are going to need to understand not just how much AI they’re consuming, but what they’re getting from it.
If you’re spending millions on AI tokens, you need to know what those tokens are actually achieving. Otherwise, you’re just measuring consumption and that’s only part of the story.
One final thought
Microsoft has just finished another enormous year.
$331.8 billion of revenue
$133.7 billion of net income
$100 billion+ of Azure revenue
30 million+ paid Copilot seats
Tens of billions being invested in the infrastructure needed to support the next phase of AI.
Microsoft is becoming a business that combines licensing and consumption.
For all of us working in ITAM, FinOps, and/or Microsoft licensing, understanding how those two worlds come together is going to be increasingly important.
Minor update to Responsible Use of Microsoft AI Services Web IQ added to Privacy & Security terms M365 G3 & G5 added as eligible pre-requisites for M365 Copilot Minor renaming of Microsoft Defender Expert services Updates to terms around Professional Services
Slightly bigger is the clarification/addition to terms that customers with SA who enable Azure Arc are eligible for ESU (Extended Security Updates).
There are some other changes that weren’t in the Product Terms:
A robot wearing a GitHub Copilot Workshop vest stands in a busy office with people collaborating in the background.
Microsoft have announced General Availability of a new feature within Copilot Studio – the GitHub Copilot harness. This sits alongside the already available Standard harness and Copilot Chat harness.
This new capability means your in-house created agents can now use the same coding and reasoning capabilities as Copilot Cowork and GitHub Copilot – putting new capabilities on the table for your AI agents.
While that is all well and good I would, not surprisingly, like to focus in on a licensing/pricing change. The Microsoft post casually states:
“Agents running on the GitHub Copilot harness use usage-based billing for all work, regardless of Microsoft 365 Copilot licensing.”
That, potentially, has quite the impact. Agents built using the 2 existing harnesses have their Copilot Credits covered by a user’s M365 Copilot license – this is not the case when agents are built with the GitHub Copilot harness. This means those agents will use Copilot Credits and burn pre-purchased amounts or incur PAYG costs.
To be clear, Microsoft aren’t removing anything or forcing this more expensive model on customers; the GitHub Copilot harness is a new, additional option that organisations can choose to use, or not. However it does add another potential way for people to inadvertently spend money with Microsoft and thus further highlights the need for storng internal governance and awareness/training programs.